The Practical Guide to Becoming Smarter with Money and Building Long-Term Wealth
Money plays an important role in almost every part of our lives. It affects our lifestyle, family responsibilities, business decisions, education, future plans and personal freedom. Yet many people spend years earning money without ever learning how to manage it properly.
Some individuals earn a reasonable monthly income but struggle to save anything. Others run businesses with impressive sales but experience regular cash-flow problems. Many people work harder every year, hoping their financial situation will improve, but they never develop a clear strategy for managing what they earn.
The problem is not always a lack of income. Sometimes, the real problem is a lack of financial knowledge.
This is where financial literacy becomes important.
Financial literacy means understanding how money works and learning how to make better financial decisions. It includes earning, spending, saving, borrowing, investing, budgeting and planning for the future.
Becoming financially intelligent does not require a university degree or a large amount of money. It requires the willingness to learn, practical experience and consistent financial habits.
In this guide, we will explore practical ways to improve financial knowledge, manage money more effectively, increase earning opportunities and gradually build long-term financial stability.
- Understand the Difference Between Earning Money and Managing Money
One of the biggest financial mistakes people make is believing that a higher income automatically creates financial security.
Imagine two individuals.
Person A earns Rs. 200,000 per month but spends almost everything on lifestyle expenses, unnecessary purchases and short-term desires.
Person B earns Rs. 100,000 per month but follows a budget, saves regularly, avoids unnecessary debt and invests in useful skills.
Although Person A earns more, Person B may gradually develop a stronger financial position.
This teaches us an important lesson: earning money and managing money are two different skills.
A financially intelligent person understands that every rupee has a purpose. Instead of spending first and saving whatever remains, they plan their spending before the money disappears.
Practical lesson: Never measure financial success only by monthly income. Also consider savings, debts, assets, expenses and future earning potential.
- Learn the Four Basic Financial Concepts
Before exploring investments or wealth creation, understand four fundamental concepts.
Income
Income is the money you receive through employment, business, freelancing, investments or other legitimate activities.
Examples include:
- Monthly salary.
- Business profits.
- Freelancing payments.
- Rental income.
- Investment returns.
Expenses
Expenses are the costs of maintaining your lifestyle and operating your business.
Examples include:
- Food and groceries.
- House rent and utility bills.
- Education and transportation.
- Business operating expenses.
- Marketing and advertising.
Assets
Assets are resources that have economic value and can contribute to your financial position.
Examples include:
- Cash savings.
- Investments.
- Property.
- Productive business equipment.
- Business ownership.
Liabilities
Liabilities are financial obligations you owe to other people or institutions.
Examples include:
- Outstanding loans.
- Credit card balances.
- Unpaid business obligations.
- Other financial debts.
Understanding these concepts gives you a clearer picture of your financial position and helps you make informed decisions.
- Create a Monthly Budget That Actually Works
Budgeting is one of the simplest and most powerful financial habits.
A budget is not designed to prevent you from enjoying life. Its purpose is to help you enjoy your income without losing control of your finances.
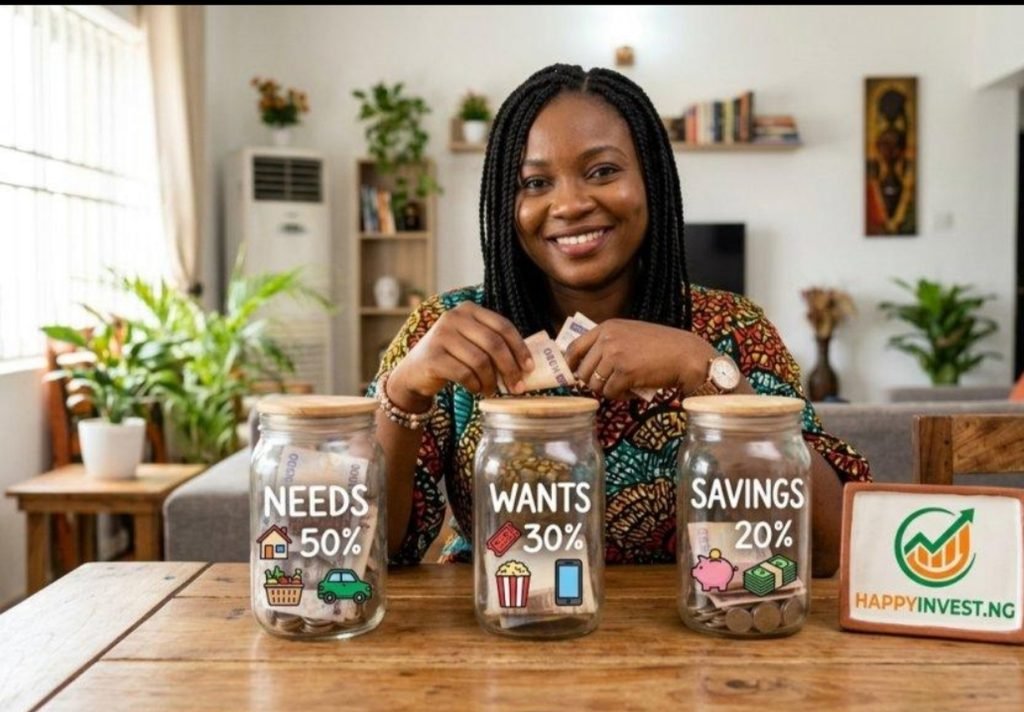
Start by recording your monthly income and dividing your money into different categories.
For example, consider someone earning Rs. 100,000 per month:
Financial Category| Allocation
Essential expenses| Rs. 50,000
Savings and investments| Rs. 20,000
Family and personal spending| Rs. 20,000
Learning and development| Rs. 10,000
Total| Rs. 100,000
This is only an illustrative budget. Your actual allocation should depend on your income, family responsibilities, debts and financial priorities.
The most important habit is tracking where your money goes.
Record even small expenses. At the end of each month, review your spending and identify unnecessary costs.
You may discover that small daily purchases are consuming a significant amount of your income.
- Build an Emergency Fund Before Taking Big Financial Risks
Life is unpredictable.
A medical expense, unexpected repair, business slowdown or temporary loss of income can create serious financial pressure.
An emergency fund helps you deal with these situations without depending entirely on loans or borrowing.
A practical target is to save enough to cover three to six months of essential living expenses.
For example, if your essential monthly expenses are Rs. 60,000, your emergency fund target could be:
- Three months: Rs. 180,000.
- Six months: Rs. 360,000.
You do not need to build this amount immediately.
Start with small, regular contributions and keep emergency money somewhere safe and accessible.
An emergency fund is not an investment for maximum profit. It is financial protection.
- Understand Good Debt and Bad Debt
Borrowing money is not automatically a bad financial decision. However, borrowing without understanding the cost and repayment obligations can create long-term problems.
Some borrowing may support productive activities, such as purchasing equipment for a profitable business. Other borrowing may finance unnecessary lifestyle expenses.
Before taking any loan, consider:
- How much will I repay in total?
- What are the interest, fees or other financing costs?
- Can I comfortably afford the repayments?
- What happens if my income decreases?
- Is this borrowing genuinely necessary?
Compare different financing options carefully, including their legal, ethical and personal implications.
Avoid borrowing simply to maintain a lifestyle that your income cannot support.
- Learn How Inflation Affects Your Money
Inflation gradually reduces the purchasing power of money.
Imagine that Rs. 10,000 can purchase a particular collection of goods today. If prices increase over time, the same Rs. 10,000 may purchase fewer goods in the future.
This means keeping all your money without considering inflation can affect your long-term financial position.
Financially intelligent people understand the importance of protecting their purchasing power.
Learn about:
- Inflation and purchasing power.
- Savings returns.
- Investment risks.
- Diversification.
- Long-term financial planning.
Never assume that every investment automatically beats inflation. Compare expected returns with costs, taxes, risks and inflation.
- Understand Investing Before You Invest
Investing is one possible way to build wealth over time, but it requires knowledge, patience and risk management.
There are different investment opportunities, each with its own benefits and risks.
Stocks and Shares
Stocks represent ownership in a company. Their prices can increase or decrease depending on business performance, market conditions and investor expectations.
Mutual Funds
Mutual funds collect money from multiple investors and invest it according to a defined strategy. They can provide diversification, although returns are not guaranteed.
Government Securities
Government securities are financial instruments issued by governments. Their returns, maturity periods and risks depend on the specific instrument and issuing government.
Real Estate
Property may provide rental income and potential long-term appreciation. However, it requires careful consideration of location, legal ownership, maintenance and liquidity.
Business Investment
Investing in your own business can create opportunities for growth, provided you understand operating costs, customer demand and profitability.
Important: Never invest money simply because someone promises guaranteed high returns. Verify the investment, understand the risks and avoid schemes that depend on recruiting other people or promising unrealistic profits.
- Develop Multiple Income Streams
Relying on a single source of income can create financial vulnerability.
If that source disappears, your entire financial situation may be affected.
Developing additional income sources can improve financial resilience.
Some opportunities include:
Freelancing: Offer professional services such as graphic design, content writing, web development, SEO, digital marketing or virtual assistance.
E-commerce: Sell suitable products through online marketplaces or your own website.
Digital Products: Create templates, educational materials, downloadable resources and other useful digital products.
Content Creation: Develop valuable content through websites, blogs, videos or other platforms. Income may come from advertising, sponsorships, subscriptions or products, depending on eligibility and audience demand.
Business Development: Expand an existing business by improving services, reaching new customers and creating additional revenue opportunities.
Remember that multiple income streams do not mean starting ten businesses simultaneously.
Start with one opportunity, develop the necessary skills, build a reliable system and expand when the first source becomes stable.
- Financial Literacy Is Essential for Business Owners
Business owners need financial knowledge just as much as individuals managing household finances.
A business can generate significant revenue and still experience financial difficulties.
Why?
Because revenue is not the same as profit, and profit is not always the same as available cash.
For example:
A business generates Rs. 500,000 in monthly sales.
Its expenses are:
- Product and service costs: Rs. 250,000.
- Salaries: Rs. 80,000.
- Marketing: Rs. 40,000.
- Rent and utilities: Rs. 30,000.
- Other expenses: Rs. 20,000.
Remaining operating profit before applicable taxes and other adjustments:
Rs. 80,000.
This example demonstrates why business owners must monitor expenses rather than focusing only on sales figures.
Every business should maintain proper records of:
- Sales and revenue.
- Operating expenses.
- Customer payments.
- Supplier payments.
- Outstanding invoices.
- Cash flow.
- Profit and loss.
- Taxes and financial obligations.
Good financial records help business owners identify problems early and make better decisions.
- Invest in Financial Education and Valuable Skills
One of the most valuable investments you can make is developing skills that improve your ability to earn.
Financial knowledge helps you manage money, while professional skills help you create earning opportunities.
Consider learning:
- Financial planning.
- Accounting fundamentals.
- Excel and financial spreadsheets.
- Digital marketing.
- Business management.
- Sales and communication.
- Artificial intelligence tools.
- E-commerce management.
- Project management.
The combination of financial knowledge and professional skills can create significant opportunities.
However, remember that completing a course does not guarantee income. Practical experience, market demand, quality work and customer relationships also matter.
- Use Technology to Manage Your Money
Modern technology makes financial management easier.
You can use digital tools to record income, track expenses, monitor business performance and organize financial documents.
Useful options include:
Google Sheets: Create monthly budgets, expense records and savings trackers.
Microsoft Excel: Build financial reports, calculate profit margins and analyze business performance.
Accounting Software: Manage invoices, expenses and financial records.
Banking Applications: Monitor transactions, transfers and account balances through official banking channels.
Budgeting Applications: Organize personal and household expenses.
Choose tools according to your requirements and protect your financial information with strong passwords and two-factor authentication where available.
- Avoid Common Financial Mistakes
Many financial problems develop because of repeated mistakes rather than one major decision.
Here are some habits to avoid:
- Spending more than you earn.
- Ignoring small daily expenses.
- Taking loans without understanding repayment costs.
- Investing without researching the opportunity.
- Following unrealistic get-rich-quick promises.
- Mixing personal and business finances.
- Ignoring financial records.
- Depending on one income source forever.
- Delaying financial education.
- Making investment decisions based on emotions or social pressure.
Financial intelligence is not about making perfect decisions every day. It is about learning from mistakes and developing better habits over time.
- Your 90-Day Financial Literacy Action Plan
Knowledge becomes valuable when you apply it.
Here is a simple three-month plan to begin improving your financial position.
First 30 Days: Understand Your Money
- Record all income sources.
- Track daily expenses.
- Calculate your monthly spending.
- Identify outstanding debts.
- Create a realistic monthly budget.
- Set your first savings target.
Days 31–60: Build Financial Protection
- Start an emergency fund.
- Review unnecessary expenses.
- Understand inflation.
- Learn basic accounting.
- Separate personal and business finances.
- Research legitimate savings and investment options.
Days 61–90: Focus on Growth
- Study investment fundamentals.
- Develop a valuable professional skill.
- Explore an additional income opportunity.
- Review business profitability if applicable.
- Create a one-year financial goal.
- Measure your progress.
At the end of 90 days, you should have a much clearer understanding of your financial position and the steps required to improve it.
- Financial Freedom Starts with Better Decisions
Financial freedom does not necessarily mean becoming extremely wealthy.
It means developing enough financial stability and resources to make important life decisions without constant financial pressure.
For one person, financial freedom may mean paying household expenses comfortably. For another, it may mean running a profitable business, supporting family members, owning productive assets or having enough savings to work without depending on every monthly payment.
There is no single definition that applies to everyone.
However, the foundation remains similar:
- Earn responsibly.
- Spend wisely.
- Save consistently.
- Manage debt carefully.
- Build useful skills.
- Invest with knowledge.
- Protect your assets.
- Plan for the future.
Small financial decisions, repeated consistently, can create meaningful long-term results.
How FAOS Can Support Your Financial Growth Journey
At FAOS – Fayyaz Ahmad Online Services, we believe that business growth and financial progress require knowledge, technology and practical action.
The digital economy offers opportunities for individuals and businesses to improve their reach, develop professional skills and explore new sources of income.
Our services are designed to support businesses and individuals through:
Website Development: Establish a professional online presence and create opportunities to reach customers.
Digital Marketing: Improve business visibility and connect with relevant audiences.
Search Engine Optimization: Help businesses improve their search visibility and build long-term online reach.
Social Media Management: Develop a consistent digital presence and communicate effectively with potential customers.
E-commerce Solutions: Support businesses interested in selling products through online channels.
Business Automation and AI Solutions: Explore ways to reduce repetitive tasks and improve business workflows.
Our approach is based on practical solutions, professional development and helping businesses adapt to an increasingly digital world.
Financial progress is a journey, and every journey begins with understanding where you stand today.
Final Thoughts
Becoming financially literate is not a one-day achievement. It is a continuous learning process that changes the way you think about earning, spending, saving and investing.
You do not need to wait until you have a large income to start managing money intelligently.
Start with what you have.
Understand your expenses. Create a budget. Build savings. Learn valuable skills. Explore income opportunities. Make informed financial decisions.
Most importantly, do not measure your progress only by how much money you earn. Measure it by how effectively you manage, protect and grow what you have.
Remember: Financial success is not just about making more money. It is about making better decisions with the money you earn.
Frequently Asked Questions (FAQs)
- What is financial literacy in simple words?
Financial literacy means understanding how to earn, manage, save, borrow and invest money responsibly.
- How can I become financially literate without a degree?
Start by learning budgeting, saving, debt management, basic accounting and investment fundamentals. Apply this knowledge to your everyday financial decisions.
- How much of my income should I save?
There is no universal percentage. Saving 10–20% can be a useful starting target if your essential expenses and financial obligations allow it.
- What is the difference between saving and investing?
Saving generally means keeping money accessible for future needs, while investing involves putting money into assets with the expectation of earning a return while accepting some level of risk.
- Can financial literacy help small business owners?
Yes. It helps business owners understand revenue, expenses, profit, cash flow, pricing and financial planning.
- How long does it take to become financially intelligent?
You can learn basic financial concepts within weeks, but becoming confident at applying them takes continuous practice and experience.
- Is financial freedom possible with a small income?
It can be possible over time. The process may be slower, but budgeting, skill development, responsible saving and gradual income growth can improve financial stability.
- What is the first step towards financial freedom?
Understand your current financial position. Calculate your income, expenses, debts and savings before setting realistic financial goals.
FAOS – Fayyaz Ahmad Online Services
Digital Solutions for Businesses That Want to Grow.
Website: https://faosok.com